Image source: AutoNation
To cancel an AutoNation product (like GAP or a Vehicle Protection Plan), you must bypass local dealership delays by contacting the AutoNation Shared Service Center (SSC) directly. Email your cancellation request, VIN, current odometer reading, and original contract number to productcancellations@autonation.com. Always demand an "SSC Case Number" to prove your request was logged. If your vehicle is financed, expect the pro-rated refund to be sent to your lienholder within 4 to 8 weeks, which will reduce your principal loan balance but will not lower your monthly payment.
Purchasing a vehicle often comes with a flurry of paperwork, and it is incredibly common for buyers to drive off the lot only to realize they agreed to thousands of dollars in optional Finance and Insurance (F&I) products. Whether it is Guaranteed Asset Protection (GAP), a Vehicle Protection Plan (VPP), or Tire & Wheel coverage, you have the legal right to cancel most of these products.
However, executing a product cancellation through AutoNation can be notoriously difficult. Customers frequently report being trapped in "bogus" phone queues, dealing with unreturned voicemails, and facing finance managers who actively stall the paperwork. This friction is not accidental; finance managers often lose their commission if a product is cancelled within the first 90 days, creating a direct conflict of interest.
The primary goal of this guide is to provide you with the direct path to the AutoNation Shared Service Center (SSC). By understanding how AutoNation's corporate structure processes these refunds, you can bypass local dealership friction, submit the correct documentation on your first try, and track your money until it successfully reaches your account.
Before you pick up the phone or draft an email, you must gather specific documentation. AutoNation's corporate processing center handles thousands of requests daily across the country. If your submission is missing a single piece of required data, it will be kicked back to the bottom of the queue, delaying your refund by weeks.
First, you need your Vehicle Identification Number (VIN) and a current odometer reading. The odometer reading is arguably the most critical piece of information for any cancellation requested after the initial 30-to-60-day full-refund window. Because most service contracts and protection plans are pro-rated based on time or mileage (whichever is greater), the exact mileage on the day you request the cancellation dictates the exact dollar amount of your refund. If you are cancelling remotely, you may be required to provide a certified odometer statement or a clear photograph of your dashboard.
Second, you must locate your Original Contract Number. This is not your vehicle loan account number. When you purchased your F&I products, you signed a separate agreement for each one (e.g., one for GAP, one for the Vehicle Protection Plan). The contract number is typically found at the top right corner of the specific product agreement. If you cannot find your physical paperwork, you will need to request a copy of your "deal jacket" from the selling dealership's finance department.
Finally, you need your complete Lienholder Information. If you financed your vehicle, AutoNation does not care about your personal mailing address for the refund check. Legally, the bank that holds your auto loan owns the vehicle and the attached products. You must provide the exact name, mailing address, and your loan account number for your lienholder so the Shared Service Center can route the funds correctly.
One of the most common mistakes consumers make is assuming that all AutoNation products follow the same cancellation rules. They do not. The rules vary wildly depending on the specific product, the administrator of the plan, and the state in which you purchased the vehicle.
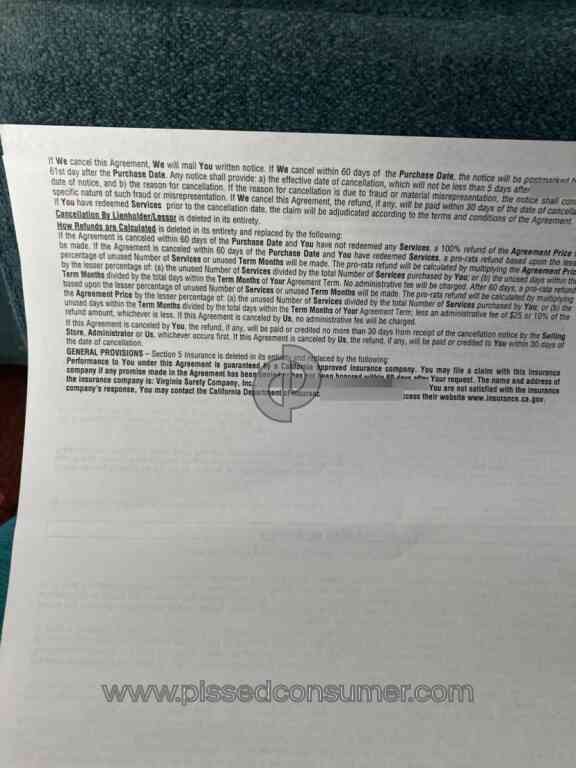
The golden rule of F&I cancellations is the "Back of the Agreement" Rule. According to official AutoNation documentation, every single product contract has a dedicated "Cancellation" section, usually printed on the reverse side of the signature page. This section outlines your exact legal rights, the calculation method for your refund, and any cancellation fees that apply.
In many jurisdictions, consumer protection laws mandate a 60-Day Full Refund Window. For example, if you purchase a vehicle in California, state law generally requires that you receive a 100% full refund (minus a small, legally capped cancellation fee, often around $50 or waived entirely) if you cancel within the first 60 days and have not filed a claim. Other states may offer a 30-day window. If you are within this window, time is of the essence. You must get your cancellation request postmarked or digitally timestamped before the deadline expires.
If you miss the full refund window, you enter the realm of Pro-Rata Calculations. A pro-rated refund means you are refunded for the unused portion of the product. The calculation is typically based on the percentage of time elapsed or the percentage of mileage used—whichever results in a smaller refund. For instance, if you bought a 60-month/60,000-mile warranty and cancel after 30 months (50% of time) but have driven 45,000 miles (75% of mileage), your refund will be based on the 25% of mileage remaining, minus a cancellation fee.
When you call the dealership where you bought the car, the receptionist will almost always transfer you to the Finance Manager. As established, the Finance Manager has a financial incentive to delay your cancellation. To bypass this, you need to communicate directly with the AutoNation Shared Service Center (SSC), which handles the actual treasury and contract processing for the entire network.
Do not rely solely on the local dealership. Use these direct corporate channels to establish a paper trail and force action:
productcancellations@autonation.com (Always use this to create a timestamped paper trail).When you use the email address provided above, do not just send a blank message asking for help. Write a formal, declarative email stating: "I am exercising my right to cancel the following products attached to VIN [Your VIN]. Please find attached my current odometer reading and a copy of my contract. I expect a cancellation form to be generated and an SSC Case Number provided to me within 48 hours."
This level of specificity signals to the corporate representatives that you understand the process and will not be easily deterred by standard delay tactics.
Successfully cancelling an AutoNation product requires a combination workflow. You cannot simply make a phone call and assume the job is done. You must manage the process from the initial request all the way to the lienholder's principal reduction.
Your first step is to obtain the official "AutoNation Shared Service Center Cancellation Request Form." You can request this via the corporate email listed above, or by walking into the finance department of any AutoNation dealership (it does not have to be the exact store where you bought the car, though the original store is preferred). The form requires you to list the specific products you are cancelling, your vehicle details, and your signature.
This is the most critical power-user tip in this entire guide. When a finance manager or a phone representative tells you, "I've submitted your cancellation," do not take their word for it. AutoNation's internal software generates a specific tracking number when a cancellation is actually pushed to corporate.
Do not leave the dealership or hang up the phone without asking for your "SSC Case Number" or "Request ID." If they cannot provide this number, it means the paperwork is still sitting on their desk and has not been submitted to the Shared Service Center. Having this number allows you to call corporate and track the exact status of your refund.
Once you have the form, you must sign it. While AutoNation has modernized and allows e-signatures for many remote cancellations, some states still legally require a "wet signature" (physical ink on paper) to cancel financial contracts. If you are dealing with an unresponsive dealership, print the form, sign it in ink, and mail it to the dealership's General Manager via USPS Certified Mail with a Return Receipt Requested. Simultaneously, scan the signed document and email it to the corporate cancellations email address. This creates an undeniable legal record that you initiated the cancellation on a specific date, locking in your pro-rated refund amount.
Not all F&I products are created equal. Some are easily refundable, some are pro-rated, and others are notoriously difficult to cancel because they involve physical modifications to the vehicle.
| Product Type | Cancellability Status | Refund Structure |
|---|---|---|
| GAP Insurance | Fully Cancellable | 100% within 30-60 days; strictly pro-rated thereafter. Refund always goes to lienholder if loan is active. |
| Vehicle Protection Plan (VPP) | Fully Cancellable | Pro-rated based on time or mileage (whichever is greater) minus a cancellation fee (usually $50). |
| Tire & Wheel Protection | Usually Cancellable | Pro-rated. May be non-cancellable in certain states if a claim has already been filed. |
| Appearance Protection | Highly Contested | Dealers claim it is non-cancellable once applied. However, the warranty portion is often refundable. |
Let’s take a deep dive into Appearance Protection, as this is where consumers face the most friction. Appearance Protection typically consists of a chemical sealant sprayed on the paint and a fabric protector applied to the interior. When you try to cancel this, the dealer will almost always say, "We cannot cancel this because the product has already been applied to the vehicle."
This is a half-truth. You are actually paying for two things: the physical chemical application (which costs the dealer very little) and the multi-year warranty backing it up (which makes up the bulk of the cost). The specific rebuttal you must use is: "I understand the chemical has been applied. However, I am cancelling the warranty policy attached to the product. According to the administrator's contract, the warranty portion is subject to a pro-rated refund."
If they still refuse, demand to see the repair order (RO) proving the chemical was actually applied by the service department before you took delivery. Often, dealers charge for this product in the finance office but forget to actually have the service technicians apply it. If there is no RO proving application, they owe you a 100% refund.
Understanding where your money goes is crucial to avoiding unnecessary frustration. The most common complaint online regarding AutoNation cancellations is from customers who wait months for a check in the mail, only to find out a check was never coming to them in the first place.
This is known as the Lienholder Trap. If your vehicle is financed, the F&I products were rolled into your auto loan. Therefore, the bank paid AutoNation for those products, not you. When you cancel, AutoNation is legally obligated to send the refund directly to your lienholder.
When the lienholder receives the funds, they apply it as a Principal Reduction. This is a vital concept to grasp: cancelling a $2,000 warranty will not lower your $450 monthly car payment. Your monthly payment is fixed by the original amortization schedule. Instead, the $2,000 refund reduces your total principal balance, meaning you will pay off the loan several months earlier than originally scheduled, saving you money on interest.
If your loan is completely paid off, or if you paid cash for the car, the refund will come directly to you via check. However, you must provide proof. According to AutoNation's payoff requirements, you must submit a "Paid in Full" letter from your bank or a copy of the vehicle title showing no active liens before they will cut a check in your name.
Despite following all the rules, you may still encounter a situation where your refund is stalled. This usually happens at the dealership level before the paperwork ever reaches the Shared Service Center.
Finance managers earn a significant portion of their income through commissions on the products they sell. However, most dealerships have a "chargeback" window—typically 90 days. If you cancel a product within that 90-day window, the finance manager loses their commission. Consequently, some unscrupulous managers will "lose" your paperwork or delay submitting it until day 91. To combat this, always get the SSC Case Number (as mentioned in Step 2) and follow up directly with corporate within 72 hours of your initial request.
If 30 days have passed and corporate has no record of your cancellation, it is time to escalate. Filing a formal complaint with the Better Business Bureau against the specific AutoNation dealership (not just the corporate entity) is highly effective. Dealership General Managers monitor their BBB ratings closely because it impacts their local reputation and franchise standing. A BBB complaint often bypasses the finance department entirely and lands on the desk of the General Manager, who will usually resolve the issue within 48 hours to have the complaint closed.
If your refund is delayed beyond 90 days, you are likely dealing with a violation of state consumer protection laws. According to legal experts on platforms like JustAnswer, your final recourse is to file a complaint with your State Attorney General’s Consumer Fraud Division. When you file this complaint, send a copy of it via certified mail to the dealership's General Manager. The threat of state regulatory scrutiny is the ultimate leverage and will almost always result in the immediate overnighting of your refund check to your lienholder.
productcancellations@autonation.com. You will still need to sign a formal cancellation document, which can often be done via e-sign depending on your state's laws.Cancelling an AutoNation product requires persistence and an understanding of how corporate processing works. Dealerships act as the middlemen, but the Shared Service Center holds the actual power to process your refund. By bypassing local delays and providing exact documentation, you can secure the money you are owed.
productcancellations@autonation.com to establish a timestamped paper trail.